Demand for mechanical, electrical, and plumbing work in Myanmar in 2026 sits inside a construction cycle that is under pressure. GlobalData projects Myanmar’s construction industry to decline by 0.6% in real terms in 2026, citing ongoing political instability, rising geopolitical trade tensions, and weaker investor confidence. This matters for MEP contractors because many electrical and plumbing scopes are tied to project starts and fit-out activity. At the same time, the same sources flag longer-range drivers that can still pull specialized contractors into active packages, especially when projects connect to energy, transport, and manufacturing investment themes over the remainder of the forecast period.
Investment conditions also shape the Myanmar MEP contracting market, because private-sector job flow often follows capital formation and import-driven procurement. According to the Directorate of Investment and Company Administration (DICA), Myanmar secured MMK835.8 billion ($398 million) in foreign direct investment (FDI) in the first 10 months of FY2025-26 (April 1, 2025, to March 31, 2026). The same comparison point in FY2024-25 was MMK656.2 million ($222.2 million). GlobalData links the period’s uncertainty to geopolitical and internal political conditions, and notes that in mid-March 2026 Myanmar’s Ministry of Foreign Affairs said the country faced challenges from economic instability, geopolitical upheaval, and climate change. These signals can affect whether projects proceed, pause, or re-scope MEP packages.
Power Expansion Targets That Can Pull Through Electrical Demand
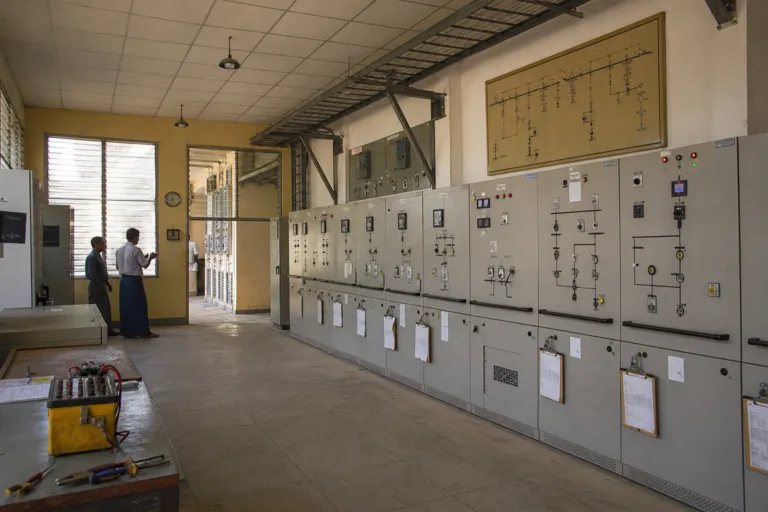
Even with a 2026 construction dip, the clearest medium-term pull for electrical scope is Myanmar’s power plan. Myanmar’s National Electrification Master Plan targets an increase in electricity production capacity from approximately 6,000MW in 2024 to 12,000MW by 2030. GlobalData also states that the government is committed to phasing out coal completely by 2050 and is drafting a new 20-year energy development plan covering 2026–45 to expand clean energy. For MEP contractors, these targets can translate into demand for power distribution work, substation-related construction interfaces, and electrical systems that support new or upgraded capacity, even when building construction is more cyclical.
Component availability and consumption concentration also matter because Myanmar’s electrical supply chain is described as import-based. IndexBox reports that Myanmar’s market for electrical circuit prefabricated elements, connectors, contact elements, and other equipment is influenced by regional supply chains, particularly from China, Thailand, and Vietnam. It also estimates household electrification at 50–60%, with demand expanding through grid extension programs but remaining concentrated in urban and peri-urban areas. Yangon Region, Mandalay Region, and Naypyidaw are estimated to account for 55–65% of national consumption of electrical components. For contractors, that concentration implies where electrical retrofit, distribution, and building-wiring work is most likely to be sustained when overall construction activity is uneven.
Looking beyond Myanmar, global benchmarks help frame what clients may expect from MEP delivery in 2026, without implying local market size. Fortune Business Insights notes the commercial end-user segment is expected to account for 59.48% of the market in 2026 (global context), and states Asia Pacific contributed 42.90% to the global market in 2025, valued at USD 68.16 billion, and is projected to reach USD 73.61 billion in 2026. Separately, The Business Research Company reports the global mechanical electrical and plumbing software market size stood at $6.1 billion in 2026 and is projected to reach $9.51 billion by 2030. In practice, these global signals reinforce that energy-efficient systems, documentation, and coordinated design workflows are increasingly central to winning and executing complex scopes.
What is the construction outlook in Myanmar in 2026, and why does it matter for MEP services?
What electrification targets could influence Myanmar’s electrical contracting demand through 2030?
Where is electrical component consumption concentrated inside Myanmar?
How does foreign direct investment relate to the Myanmar MEP contracting market in 2026?
What global indicators suggest how client expectations for MEP delivery are evolving?