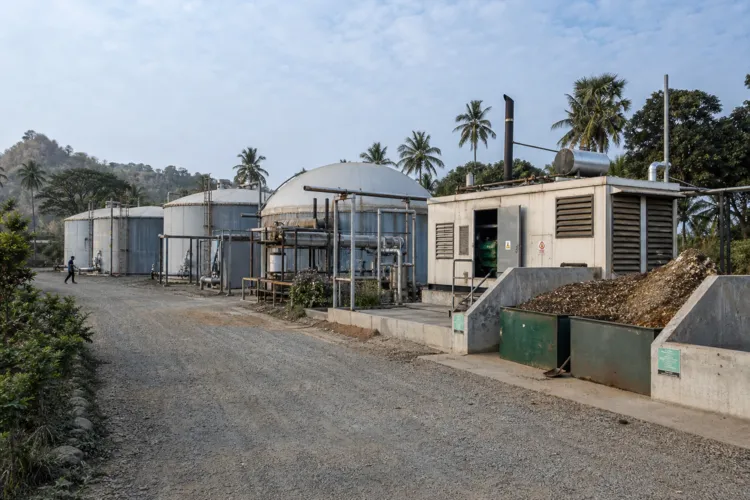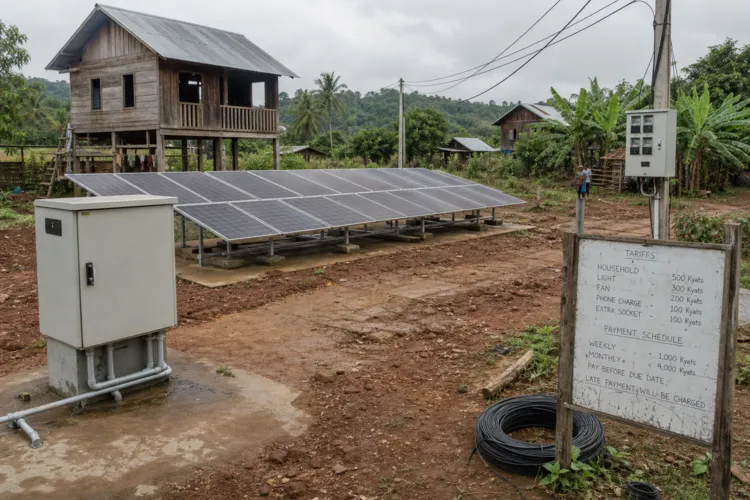
Myanmar’s power crisis continues to shape how households and businesses think about reliability in 2026. Research on Myanmar’s post-2021 conditions describes persistent load shedding, with grid electricity often available for only a few hours per day. In that context, backup power is not only a convenience. It becomes an operating requirement for essential loads, from small businesses to critical services, and it pulls more attention toward battery-based solutions, including behind-the-meter systems paired with solar PV.
Field data from Yangon shows why interest in battery storage is not only theoretical. A study using one year of 5-minute operational data from a 22 kWp grid-connected PV-battery system found PV supplied 47.1% of load, while PV plus storage covered about 77% of peak hours. The same study reported an LCOE of 0.234 USD/kWh and a blended payback range of 8.46 to 6.06 years, using an outage-conditioned approach that separates grid-time from outage-time value. These figures create a practical reference point for resilience-focused buyers assessing whether batteries can reduce diesel use while sustaining core operations.
What’s Driving Battery Buying Patterns in Myanmar in 2026
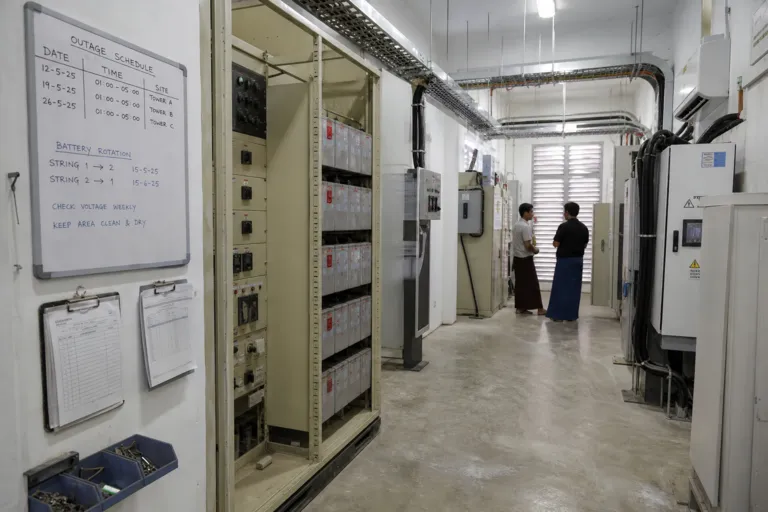
Within the Myanmar energy storage market, telecom and off-grid needs are frequently highlighted as near-term demand engines. A Myanmar battery market analysis notes that modular rack configurations for telecom backup power are pivoting buyer preference away from monolithic lead-acid blocks toward scalable lithium-ion strings. It also links procurement momentum to grid instability in rural Sagaing and Chin states, stating that tower operators now procure lithium-ion backup units as energy autonomy requirements grow. The same source points to industrial corridor density in Yangon, where manufacturing clusters and port logistics generate captive consumption for both lead-acid and advanced chemistry storage systems.
Supply structure matters as much as demand signals. IndexBox describes Myanmar’s lithium battery segment as structurally import-led within Southeast Asia’s broader energy storage and portable power landscape, stating the country does not produce lithium carbonate, lithium hydroxide, or finished lithium-ion cells at commercial scale. It adds that Myanmar lacks the precision manufacturing, clean-room infrastructure, and electrochemical expertise required for competitive cell production, making the market defined by trade flows, distribution networks, and end-use demand patterns. At the same time, the report flags that precise sizing is complicated by informal trade and mixed product categories in customs classification, even as it forecasts growth in the mid-single to low-double digits annually through 2035, with volume demand potentially doubling over the forecast horizon.
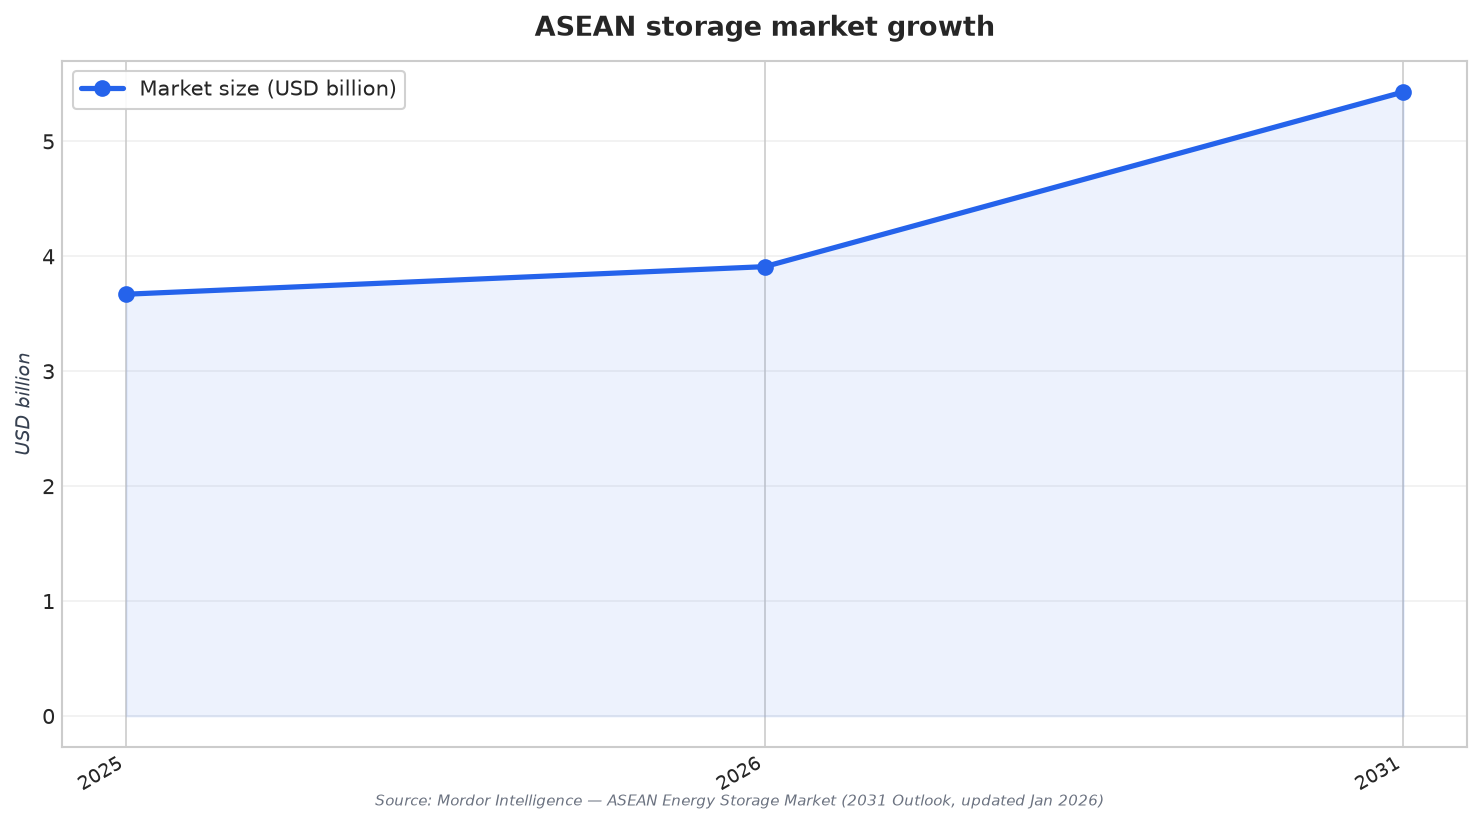
Regional context also shapes how suppliers and investors benchmark Myanmar. Mordor Intelligence projects the ASEAN energy storage market to expand from USD 3.91 billion in 2026 to USD 5.43 billion by 2031, at a CAGR of 6.76% between 2026 and 2031. In 2025, pumped-storage hydroelectricity held 80.9% of ASEAN storage technology demand, and on-grid systems accounted for 79.1% of total deployments, while off-grid storage is projected to record a 9.1% CAGR through 2031. These ASEAN-wide metrics do not describe Myanmar directly, but they underline a two-speed dynamic the same report notes: off-grid and behind-the-meter projects can move faster than long-duration utility assets, which aligns with Myanmar’s resilience-first buying logic during outages.
Why is backup power demand rising in Myanmar during 2026?
What did Yangon field data show about PV plus battery storage during outages?
Which applications are influencing battery system choices in Myanmar?
How does import dependence affect Myanmar’s lithium battery supply?
What is the outlook for the Myanmar energy storage market versus the broader ASEAN storage trend?