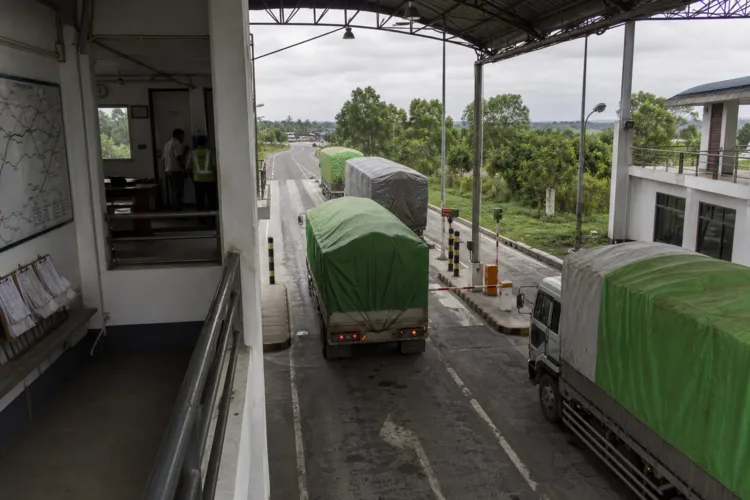

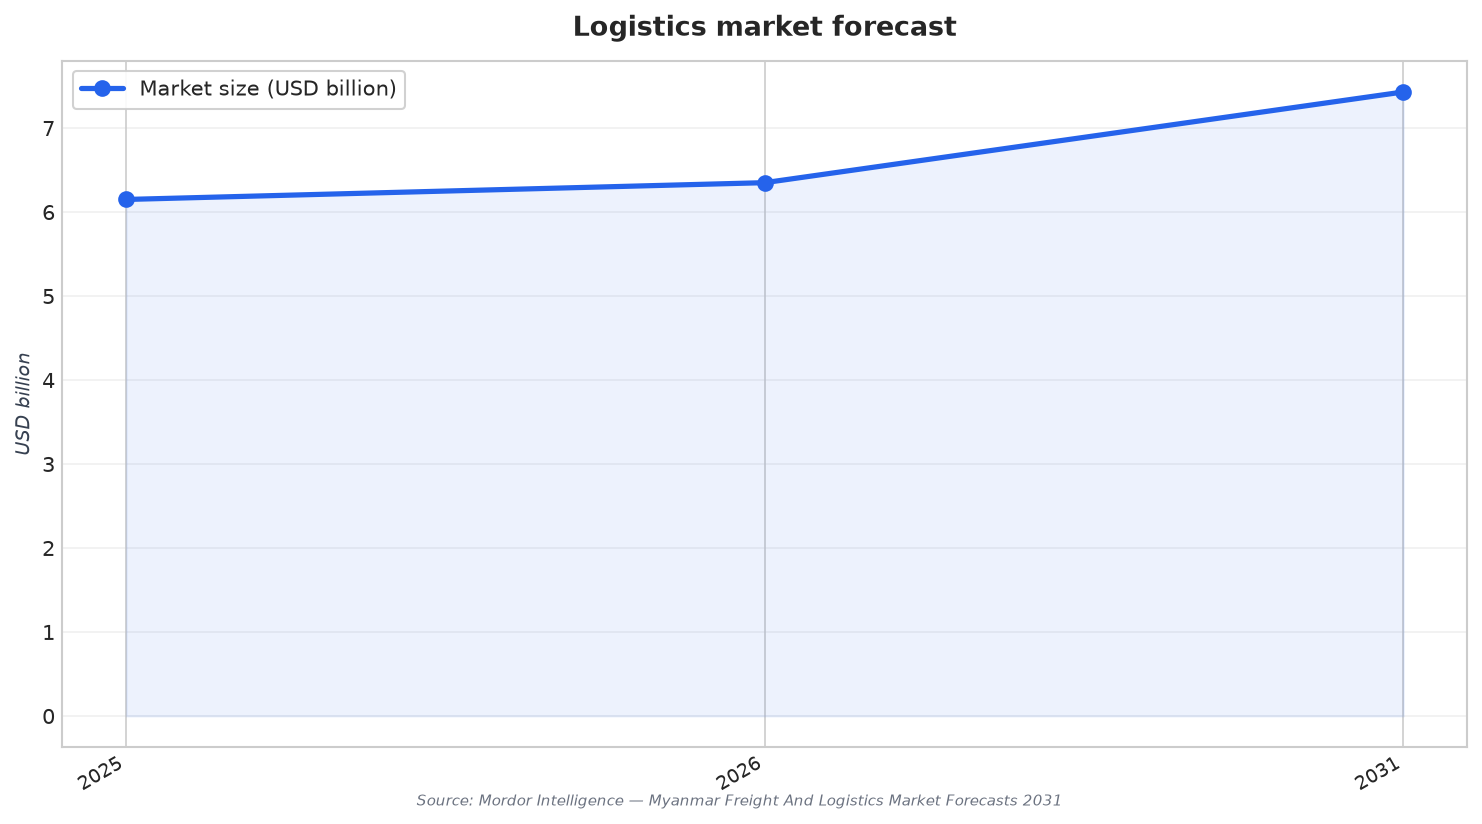
Myanmar’s parcel and express momentum in 2026 is best understood through the broader logistics baseline. Mordor Intelligence expects the Myanmar freight and logistics market to increase from USD 6.15 billion in 2025 to USD 6.35 billion in 2026, and to reach USD 7.43 billion by 2031, reflecting a 3.21% CAGR over 2026–2031. This growth is linked to Myanmar’s positioning as an overland bridge between China’s Yunnan Province and the Indian Ocean within the China-Myanmar Economic Corridor. The same source also flags headwinds that affect delivery reliability, including political instability, foreign-exchange controls, and fragmented last-mile networks.
Inside that market, Courier, Express, and Parcel services stand out for faster expansion than other logistics functions. Mordor Intelligence projects CEP services to expand at a 4.69% CAGR over 2026–2031, while freight transport led the overall market with a 60.15% share in 2025. Demand signals from online commerce add practical weight to this outlook: the same reporting cited that Myanmar had 5.9 million e-commerce users generating USD 3.80 billion in gross merchandise value. These factors help frame the Myanmar courier and express delivery market in 2026 as a growth segment, but one still constrained by network fragmentation and execution variability across cities and corridors.
Domestic Volume Leads, While Cross-Border Pace Builds
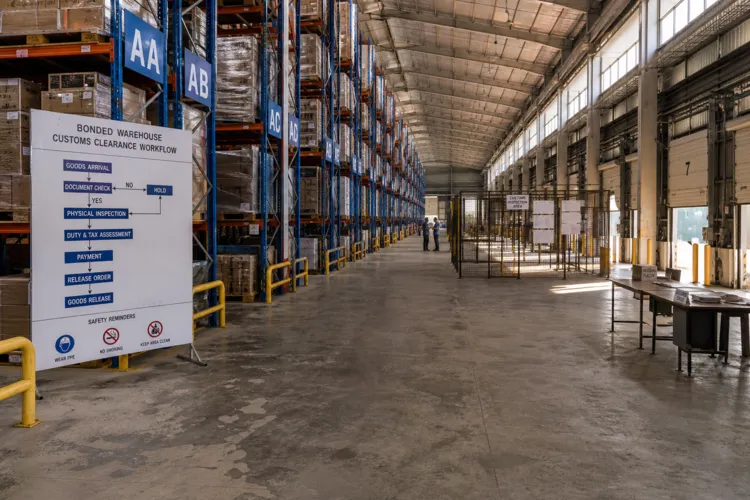
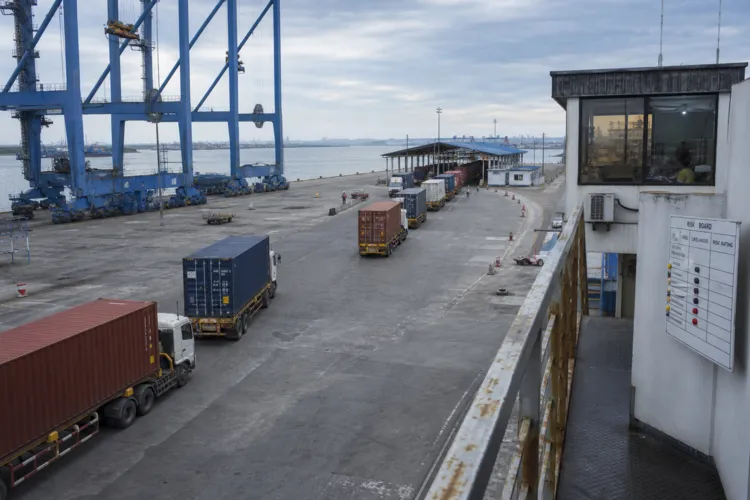
Revenue mix shows where operators can scale fastest. Domestic CEP held a 66.58% revenue share in 2025, according to Mordor Intelligence, indicating that national networks and intra-country distribution remain the primary volume engine. At the same time, international CEP is forecast to grow at a 4.88% CAGR over 2026–2031, which raises the importance of customs readiness and cross-border handoffs. MarkWide Research highlights Track & Trace technology as a leading investment priority as shippers want real-time visibility across the Thailand-Myanmar border. It also points to the Directorate of Trade’s digitization protocols compressing port clearance timelines and attracting bonded warehouse investment into Thilawa Special Economic Zone.
Capacity and mode choices also shape 2026 delivery performance. In freight forwarding, sea and inland waterways accounted for 79.02% of revenue share in 2025, while air freight forwarding is expected to grow at a 3.67% CAGR over 2026–2031. In freight transport, road captured 71.12% of segment revenue share in 2025, yet air freight transport is projected to post the fastest 4.12% CAGR over 2026–2031. Warehousing is similarly skewed: non-temperature-controlled facilities held a 91.28% revenue share in 2025, while temperature-controlled capacity is expected to grow at a 3.07% CAGR over 2026–2031, aligning with MarkWide’s note that agri-commodity exporters are contracting cold storage for perishable shipments into China and Thailand.
Company activity and infrastructure narratives provide additional context for 2026 planning. MarkWide Research describes A.P. Moller – Maersk leveraging terminal operations at Yangon Port to control container throughput capacity, while Deutsche Post DHL Group competes on customs brokerage and last-mile density in Mandalay and Yangon. At the macro level, Mordor Intelligence notes that USD 5.6 billion worth of Chinese-backed projects were announced in 2024, including the Kyaukphyu deep-sea port valued at USD 7.3 billion, alongside continued SEZ expansion and the National Single Window customs platform. For operators, the opportunity is to translate these corridor and customs improvements into more predictable line-haul flows and tighter last-mile execution in 2026.
What is the 2026 outlook for Myanmar’s courier and express delivery market?
How important is domestic delivery versus international parcels in Myanmar?
What e-commerce signals are tied to courier and parcel demand in Myanmar?
Which logistics modes matter most for delivery performance in Myanmar?